Understanding Real Estate Transactions in Connecticut
A real estate transaction is the legal process of transferring ownership of property from one party to another. In Connecticut, this process is governed by statutory law (including the Connecticut General Statutes, state conveyancing standards, and Department of Consumer Protection regulations), property law principles, and standard real estate attorney practices that ensure the transfer is legally valid and properly documented.
Most real estate transactions involve:
- A buyer and a seller
- A written purchase and sale agreement (often based on Connecticut Association of Realtors forms or attorney-drafted contracts)
- A title search and title insurance process
- Financing (in many cases)
- Statutory disclosures and property inspections
- A formal closing process handled primarily by real estate attorneys
Although the process may appear straightforward, real estate transactions often involve multiple professionals, including real estate brokers, mortgage lenders, title insurance companies, and closing attorneys.
Because property is a high-value asset, even small mistakes in documentation or procedure can lead to significant legal or financial consequences.
The Role of the Purchase Agreement
The purchase agreement (commonly referred to as the Purchase and Sale Agreement or P&S) is the foundation of any real estate transaction in Connecticut. Unlike states where standardized broker forms govern through closing, in Connecticut, parties frequently transition from a binder/initial contract to a detailed formal Purchase and Sale Agreement drafted or reviewed by real estate attorneys.
A typical purchase agreement includes:
- Purchase price
- Property description and inclusions/exclusions
- Initial deposit and earnest money details
- Comprehensive schedule of contingency dates and closing deadlines
- Title defect and municipal search review clauses
- Inspection, appraisal, and mortgage contingency deadlines
- Responsibilities, default provisions, and remedies for each party
Once signed by both parties, the agreement governs the transaction and establishes each side’s legal obligations.
In practice, most disputes in Connecticut real estate transactions arise from missed contingency deadlines, failure to satisfy mortgage commitments on time, or unclear contract terms, making strict compliance with contractual dates essential.
Earnest Money Deposits
Earnest money (often divided into an initial binder deposit and a larger deposit paid upon signing the formal Purchase and Sale Agreement) is a deposit made by the buyer to demonstrate serious intent to purchase the property.
Key points about earnest money include:
- It is typically held in an attorney’s IOLTA trust account or an escrow account managed by a listing broker
- It is applied toward the purchase price or closing costs at closing
- It is refundable if the buyer terminates the contract in strict accordance with contractual objection or contingency deadlines
- It demonstrates good faith in fulfilling the contract terms
Common contingencies and deadlines that may allow a buyer to terminate and recover earnest money include:
- Building and environmental inspection objection deadlines
- Mortgage contingency and loan commitment deadlines
- Title objection deadlines
- Common Interest Community (Condominium) document review periods
In Connecticut, earnest money disputes are governed by the specific default and escrow release provisions of the contract, typically requiring mutual release agreements or court interpleader actions if a dispute arises.
Financing in Connecticut Real Estate
Most residential real estate transactions in Connecticut involve some form of financing, typically through a mortgage lender using a legal Mortgage Instrument and Promissory Note rather than a Deed of Trust.
The financing process may include:
- Loan application and pre-approval
- Credit review
- Income and asset verification
- Property appraisal ordered by the lender
- Loan underwriting and issuance of a written Mortgage Commitment Letter
Financing contingencies in Connecticut purchase contracts protect buyers by allowing them to terminate the contract and receive their deposit back if they cannot secure a formal loan commitment by a specified date.
Cash purchases are also common, particularly in high-demand suburban Fairfield County and shoreline market segments.
Property Types in Connecticut
Real estate transactions in Connecticut involve a wide range of property types, each with its own specific legal and practical considerations.
Residential Property
Includes single-family homes, townhomes, and condominiums. Residential transactions are the most common and typically involve statutory property disclosures and standard physical/environmental inspections.
Commercial Property
Includes office buildings, retail spaces, industrial facilities, and multi-family residential complexes. These transactions utilize custom commercial contracts, extensive environmental (Phase I) due diligence, and specialized zoning reviews.
Vacant, Rural & Agricultural Land
Land transactions across Connecticut—from Litchfield County farmland to vacant parcels in the Quiet Corner—involve specific considerations such as well and septic approvals, wetlands jurisdiction (Inland Wetlands and Watercourses Act), coastal management regulations, zoning compliance, and boundary surveys.
Investment Property
Includes multi-family residential units, mixed-use buildings, and short-term vacation rentals along the Connecticut coast. Investors evaluate these based on cap rates, tenant lease assignments, security deposit transfers under Conn. Gen. Stat. § 47a-21, and local municipal regulations.
Role of Real Estate Professionals
Many Connecticut real estate transactions involve professionals who help facilitate the process under state licensing laws.
These may include:
- Licensed real estate brokers and salespersons
- Mortgage lenders and mortgage brokers
- Real estate closing attorneys (who also frequently act as title insurance agents)
- Title insurance underwriters
- Licensed home inspectors
In Connecticut, attorneys play a central and traditional role in real estate transactions. Buyers and sellers are customarily represented by independent closing attorneys who review contracts, perform title examinations, resolve title defects, prepare conveyancing documents, and handle escrow funding at closing.
Home Inspections and Due Diligence
Once a contract or binder is executed, the buyer enters a strict due diligence window governed by the inspection contingency provisions set in the agreement.
A home inspection is a vital due diligence step. A licensed Connecticut home inspector generally evaluates:
- Roof condition and structural integrity
- Foundation, basement moisture, and drainage
- Electrical, plumbing, and heating/HVAC systems
- Well water quality and flow, and septic system integrity (where applicable)
- Radon gas levels in air and water (common in Connecticut geology)
- Environmental concerns such as underground oil tanks or lead paint
If physical defects or safety issues are discovered, the buyer may:
- Submit an inspection amendment requesting specific repairs or monetary credits
- Negotiate a reduction in the purchase price
- Elect to terminate the contract before the inspection contingency deadline and receive a full earnest money refund
In Connecticut, adherence to written notice deadlines is strictly enforced; failing to object or terminate in writing before the deadline waives the buyer’s right to raise physical objections.
Title Searches and Title Insurance
Before ownership can be transferred, a title search is conducted—typically by the buyer’s closing attorney or a title abstractor—covering at least a 40-year chain of title under the Connecticut Marketable Title Act (Conn. Gen. Stat. § 47-33b et seq.).
A title search in Connecticut evaluates:
- Outstanding mortgages or equity lines of credit
- Tax liens, municipal assessment liens, or mechanic’s liens
- Recorded easements, rights-of-way, and restrictive covenants
- Probate court releases or estate tax lien clearances for prior deceased owners
- Municipal zoning, inland wetlands, and building permit compliance
If title defects or unexpected encumbrances are discovered, the seller must cure them or the buyer may submit a title objection or terminate the contract in accordance with title provisions.
To protect against hidden defects, title insurance policies (Owner’s Policy and Lender’s Policy) are issued at closing. In Connecticut, the buyer customarily pays for both the Owner’s and Lender’s Title Insurance Policies.
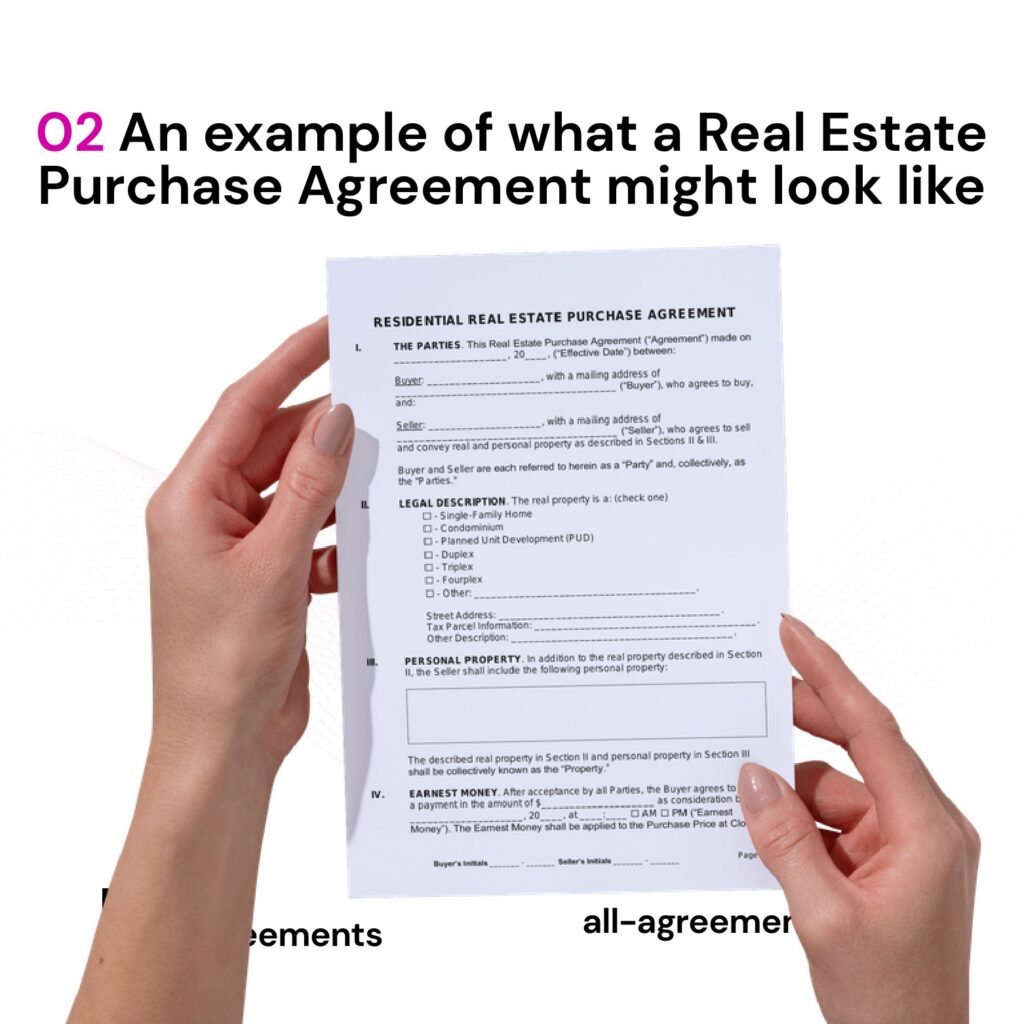
Real Estate Purchase Agreement
Purchase real estate confidently with a custom-prepared Real Estate Purchase Agreement tailored to your specific transaction.
Document purchase price, financing, contingencies, inspections, closing terms, disclosures, and buyer and seller obligations.
- Custom-Prepared Agreement: Built using your transaction details.
- Complete Purchase Terms: Covers financing, earnest money, inspections, closing, title, and possession.
- Professional Documentation: Prepared for residential, commercial, land, and investment property purchases throughout the United States.
💡 Prepared for buyers, sellers, investors, and real estate professionals across all U.S. states.
Contingencies in Real Estate Contracts
Contingencies in Connecticut real estate contracts are structured as explicit rights of inspection, review, and termination tied to strict calendar dates.
Common contract contingencies include:
Mortgage Contingency
Allows the buyer to terminate if a formal written mortgage commitment cannot be obtained by the commitment date specified in the agreement.
Inspection Contingency
Allows the buyer to evaluate the physical condition of the property, well, septic, and environmental factors, and request repairs, negotiate credits, or terminate the deal.
Title and Municipal Search Contingency
Provides the buyer time to review title searches, municipal department records (building, health, and wetlands permits), and tax records.
Common Interest Community (Condominium) Contingency
Under the Connecticut Common Interest Ownership Act (CIOA, Conn. Gen. Stat. § 47-200 et seq.), gives buyers of condominiums or HOA units a statutory right to review resale documents, association financial budgets, bylaws, and special assessment disclosures, along with a statutory right of cancellation.
These contingencies protect both parties by providing clear rules and timelines for resolving issues or exiting the transaction safely.
Closing Process in Connecticut
Closing is the final stage of a Connecticut real estate transaction where conveyancing documents are signed, funds are transferred, and legal title passes from seller to buyer.
The closing process typically includes:
- Final walkthrough inspection by the buyer prior to closing
- Execution of closing statements (Closing Disclosure or HUD-1), mortgage loan documents, and the conveyance deed (commonly a Warranty Deed or Special Warranty Deed) before a notary public or attorney
- Delivery of certified funds, bank checks, or wire transfer into the buyer attorney’s IOLTA trust account
- Payoff of existing seller mortgages, municipal liens, and closing expenses
- Recording of the Warranty Deed and Mortgage Instrument with the Town Clerk in the municipality where the property is located
- Delivery of keys and possession to the buyer as agreed in the contract
In Connecticut, real estate closings are formally conducted by closing attorneys rather than title company escrow clerks. Because Connecticut operates on a town-by-town recording system rather than a county system, documents are recorded directly with the local Town Clerk.
Once the deed is formally recorded with the Town Clerk, the buyer becomes the legal owner of the property.
Closing Costs
Both buyers and sellers incur specific closing costs, which are detailed in the Closing Disclosure or Settlement Statement.
Common buyer costs include:
- Loan origination, processing, and underwriting fees
- Appraisal and credit report fees
- Owner’s and lender’s title insurance premiums
- Home, radon, well, and septic inspection fees
- Escrow reserves for property taxes and homeowner insurance
- Recording fees for the Warranty Deed and Mortgage at the Town Clerk’s office
- Attorney legal fees
Common seller costs may include:
- Real estate broker commissions
- State and municipal real estate conveyance taxes (Connecticut imposes both a state conveyance tax and a local municipal conveyance tax under Conn. Gen. Stat. § 12-494)
- Payoff of outstanding mortgages or liens
- Attorney legal fees
- Prorated municipal real estate taxes and sewer/water assessments
- Condominium resale certificate fees
The exact allocation of closing costs is specified in the Purchase and Sale Agreement.
Common Buyer Mistakes
Navigating a Connecticut real estate purchase requires careful attention to detail. Common buyer mistakes include:
- Missing Contract Deadlines: Failing to submit a written Inspection Notice or request a Mortgage Contingency Extension prior to contractual deadlines can risk earnest money deposits.
- Overlooking Condominium Rules and Resale Packages: Failing to carefully review HOA financial reserves, pending special assessments, or leasing restrictions before the statutory cancellation window expires.
- Ignoring Environmental and Water Concerns: Neglecting radon testing, well water quality/quantity testing, or failing to check for abandoned underground oil storage tanks common in older New England homes.
- Making Major Financial Changes Before Closing: Opening new credit lines, changing employment, or making large purchases prior to closing can jeopardize final mortgage approval.
Common Seller Mistakes
Sellers in Connecticut face legal and operational risks during a property transaction, including:
- Incomplete Property Disclosures: Failing to complete the mandatory Residential Property Condition Disclosure Report accurately can lead to post-closing statutory credits or litigation.
- Ignoring Conveyance Tax Calculations: Miscalculating state or local municipal conveyance taxes (especially in municipalities with higher local rates).
- Failing to Address Title and Probate Issues: Not clearing old unreleased mortgages or missing probate court releases for inherited properties well in advance of closing.
- Unresolved Underground Tank Issues: Failing to document the proper removal or closure of underground heating oil tanks.
Seller Disclosures in Connecticut
Connecticut law requires sellers of residential property to provide specific written disclosures regarding the physical condition and statutory status of the property. Key Connecticut disclosure aspects include:
- Residential Property Condition Disclosure Report: Under Conn. Gen. Stat. § 20-327b, sellers of 1-to-4 family residential properties must furnish a completed disclosure covering structural condition, roof age, plumbing, heating, electrical, environmental hazards, and water/septic systems. Failure to provide this report results in a statutory $500 credit to the buyer at closing.
- Lead-Based Paint Disclosure: Required for residential properties built prior to 1978 in compliance with federal law.
- Common Interest Community Disclosures: Sellers of condominium units must furnish a formal Resale Certificate issued by the association under Conn. Gen. Stat. § 47-270.
Failing to disclose known material defects or misrepresenting property condition can expose sellers to legal liability after closing.
Real Estate Agent Agreement
Create a custom Real Estate Agent Agreement defining representation terms, commissions, services, and responsibilities between agents and clients.
Clearly structure real estate relationships with professional terms covering compensation, authority, disclosures, and transaction duties.
- Custom-Prepared Document: Structured using agent, brokerage, client, property, commission, and service information you provide.
- Complete Representation Terms: Document services, fees, negotiation authority, marketing responsibilities, and transaction expectations.
- Agent & Client Protection: Address termination, disclosures, expenses, disputes, and additional real estate provisions.
💡 Designed for real estate professionals and clients throughout the United States and adaptable to the governing state law and selected representation arrangement.
Contract Termination in Real Estate Transactions
A Connecticut real estate contract may be terminated under specific conditions outlined in the agreement or allowed by state statute.
Common grounds for contract termination include:
- Unsatisfactory Inspection or Environmental Findings: The buyer provides timely written notice of election to terminate based on inspection findings before the inspection deadline.
- Inability to Secure Mortgage Commitment: The buyer provides timely written notice of inability to obtain loan approval before the mortgage contingency date.
- Statutory Condominium Cancellation: Exercise of the buyer’s statutory right to cancel within the allowed window after receiving Common Interest Community resale documents.
- Title Defect Non-Cure: Failure or refusal of the seller to clear marketable title defects prior to closing.
- Default or Breach of Contract: If either party fails to perform, the non-defaulting party may pursue deposit remedies, actual damages, or specific performance in court.
Because Connecticut contracts strictly enforce notice rules, termination notices must be executed and delivered in exact accordance with contract requirements.
Real Estate Investment Considerations
Investing in Connecticut real estate offers opportunities in residential rental properties, commercial spaces, and shoreline vacation rentals, but requires specialized diligence.
Key factors investors consider in Connecticut include:
- Local landlord-tenant statutory framework (Conn. Gen. Stat. Title 47a), including strict security deposit interest and return rules (§ 47a-21) and eviction procedures.
- Local municipal mill rates and property tax reassessment cycles across different towns.
- Maintenance requirements related to New England winter weather, freeze-thaw cycles, snow loads, and coastal storms.
- Local zoning regulations and municipal short-term rental restrictions along coastal or university areas.
Successful investing depends on accurate financial underwriting, regulatory compliance checks, and clear understanding of municipal codes.
Common Legal and Practical Risks
Real estate transactions involve inherent risks that require proactive management. Key risks include:
- Title and Boundary Issues: Unrecorded easements, boundary encroachments, or unreleased historical mortgages on town land records.
- Environmental and Tank Liabilities: Undisclosed leaking underground heating oil storage tanks (USTs) or hazardous materials.
- Municipal Code and Permit Violations: Unpermitted additions, finished basements, or outstanding building code enforcement actions.
- Financing Disruptions: Unexpected appraisal shortfalls or last-minute mortgage commitment delays.
Working with experienced real estate attorneys, licensed brokers, title underwriters, and qualified home inspectors mitigates these legal and practical risks.
Best Practices for Connecticut Buyers and Sellers
Smooth and successful transactions result from careful preparation, open communication, and adherence to established legal timelines.
Recommended best practices include:
- Maintain a clear schedule of all contractual contingency dates, including inspection, title, and mortgage commitment deadlines.
- Complete thorough physical, environmental, well, and septic inspections.
- Review all title search results, municipal permit records, and condominium resale documents with your closing attorney.
- Ensure all formal contractual notices, requests, or terminations are delivered in writing within required timeframes.
- Complete the mandatory Residential Property Condition Disclosure Report accurately and honestly.
- Retain an experienced Connecticut real estate attorney early in the process to review agreements and manage closing procedures.
- Verify all wire transfer instructions directly with your closing attorney by phone prior to transferring funds to protect against wire fraud.
Whether buying a home in Hartford County, selling shoreline real estate, or acquiring commercial property, thorough planning leads to confident and successful property transfers.
Frequently Asked Questions
Do I need an attorney to buy or sell property in Connecticut?
While not explicitly mandated by statute, closing custom in Connecticut relies heavily on real estate attorneys. Buyers and sellers almost universally retain independent attorneys to draft/review contracts, conduct title searches, issue title insurance, and conduct closings.
How long does a typical real estate closing take in Connecticut?
A standard residential transaction with conventional financing typically takes 45 to 60 days from contract acceptance to closing. Cash transactions can close faster, often in 15 to 30 days.
Who pays for title insurance in Connecticut?
In Connecticut, custom dictates that the buyer pays for both the Lender’s Title Insurance Policy and the Owner’s Title Insurance Policy at closing.
How are property taxes handled at closing in Connecticut?
Property taxes in Connecticut are paid directly to individual towns. Taxes are adjusted at closing between buyer and seller based on the municipal fiscal year (typically July 1 to June 30) and local tax due dates.
What happens if the property inspection reveals major defects?
Under standard inspection contingencies, the buyer can request repairs or monetary credits, negotiate a price adjustment, or terminate the agreement and receive a full refund of earnest money deposits if an agreement cannot be reached before the deadline.
Conclusion
Real estate transactions in Connecticut follow a structured, legal process established by state law, conveyancing standards, and local practice. From binder acceptance and formal purchase agreement execution to inspection contingencies, title examination, municipal searches, and attorney-led closings, every step serves to manage risk and protect the interests of buyers and sellers.
Understanding contractual timelines, statutory disclosure requirements, property inspection procedures, and Town Clerk recording processes ensures that property transfers are executed smoothly and legally. Whether purchasing a family home, selling investment real estate, or acquiring land, thorough preparation and professional guidance provide the foundation for successful outcomes.
How It Works
Get started in just four simple steps
01
Select a document type
Choose the type of document from our catalog or contract us.
02
Provide details or requirements
Provide your specific requirements, details, and guidelines.
03
We prepare your document
Our consulting experts review your request and draft a tailored document.
04
You receive a printable file
Receive your ready-to-use, professional file in different formats.
Legal Context
Legal requirements in the state may vary depending on the type of document and situation.
Common use cases include:
- Business Agreements
- Consulting Agreements
- Personal Documents
- Real Estate Agreements
- Rental Agreements
- Packages Super Offer
Users should always ensure they select the correct document type for their specific situation.
Related Pages
United States Overview
Other States
Explore Legal Articles
Learn more about how legal documents work in the state:
- Connecticut Business Contracts Explained
- Connecticut Employment Contracts
- Connecticut Estate Planning
- Connecticut Power of Attorney Explained
- Connecticut Rental Laws Overview
- Connecticut Real Estate Transactions
- Connecticut Worker Classification
- How Connecticut Bills of Sale Work
- How Eviction Works in Connecticut
On sale products
-
Rent Receipt Template
Original price was: $14.99.$5.99Current price is: $5.99. -
Move-In Checklist
Original price was: $19.99.$8.99Current price is: $8.99. -
Move-Out Checklist
Original price was: $19.99.$8.99Current price is: $8.99. -
Landlord Reference Letter
Original price was: $19.99.$8.99Current price is: $8.99. -
Tenant Reference Letter
Original price was: $19.99.$8.99Current price is: $8.99.


